A seller in Ocala once told me she’d saved thirty grand by listing her own house. She’d also paid a buyer’s agent, covered a title policy she thought the buyer handled, and credited back four thousand in repair concessions after the inspection. Skipping a listing agent saves real money, no question. Still, FSBO costs in Florida don’t vanish just because you planted your own sign in the St. Augustine grass out front.
How Much Are FSBO Costs in Florida?
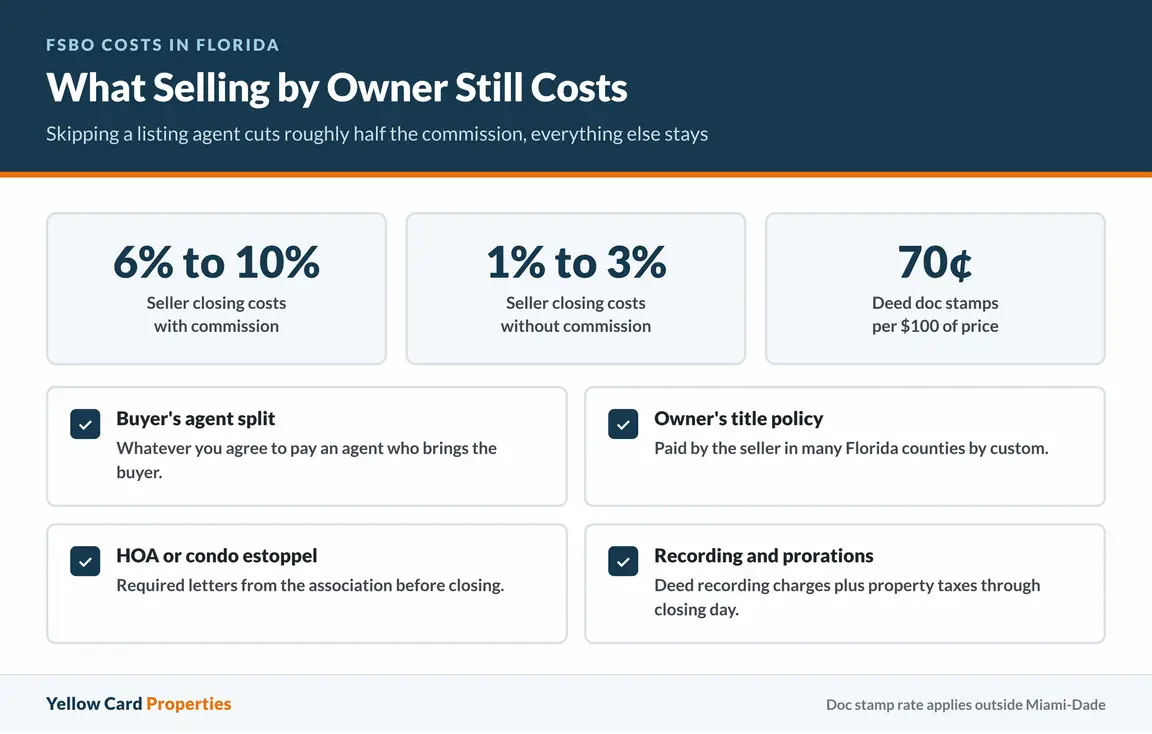
Selling without a listing agent in Florida knocks out roughly half the commission, the biggest single line on almost any settlement statement. Everything else stays put. Seller closing costs in Florida tend to land between 6 and 10 percent of the price with commission counted, or 1 to 3 percent once you strip commission out. The biggest items are the agent split, the deed doc stamp, owner’s title insurance in most counties, the HOA estoppel, and recording charges.
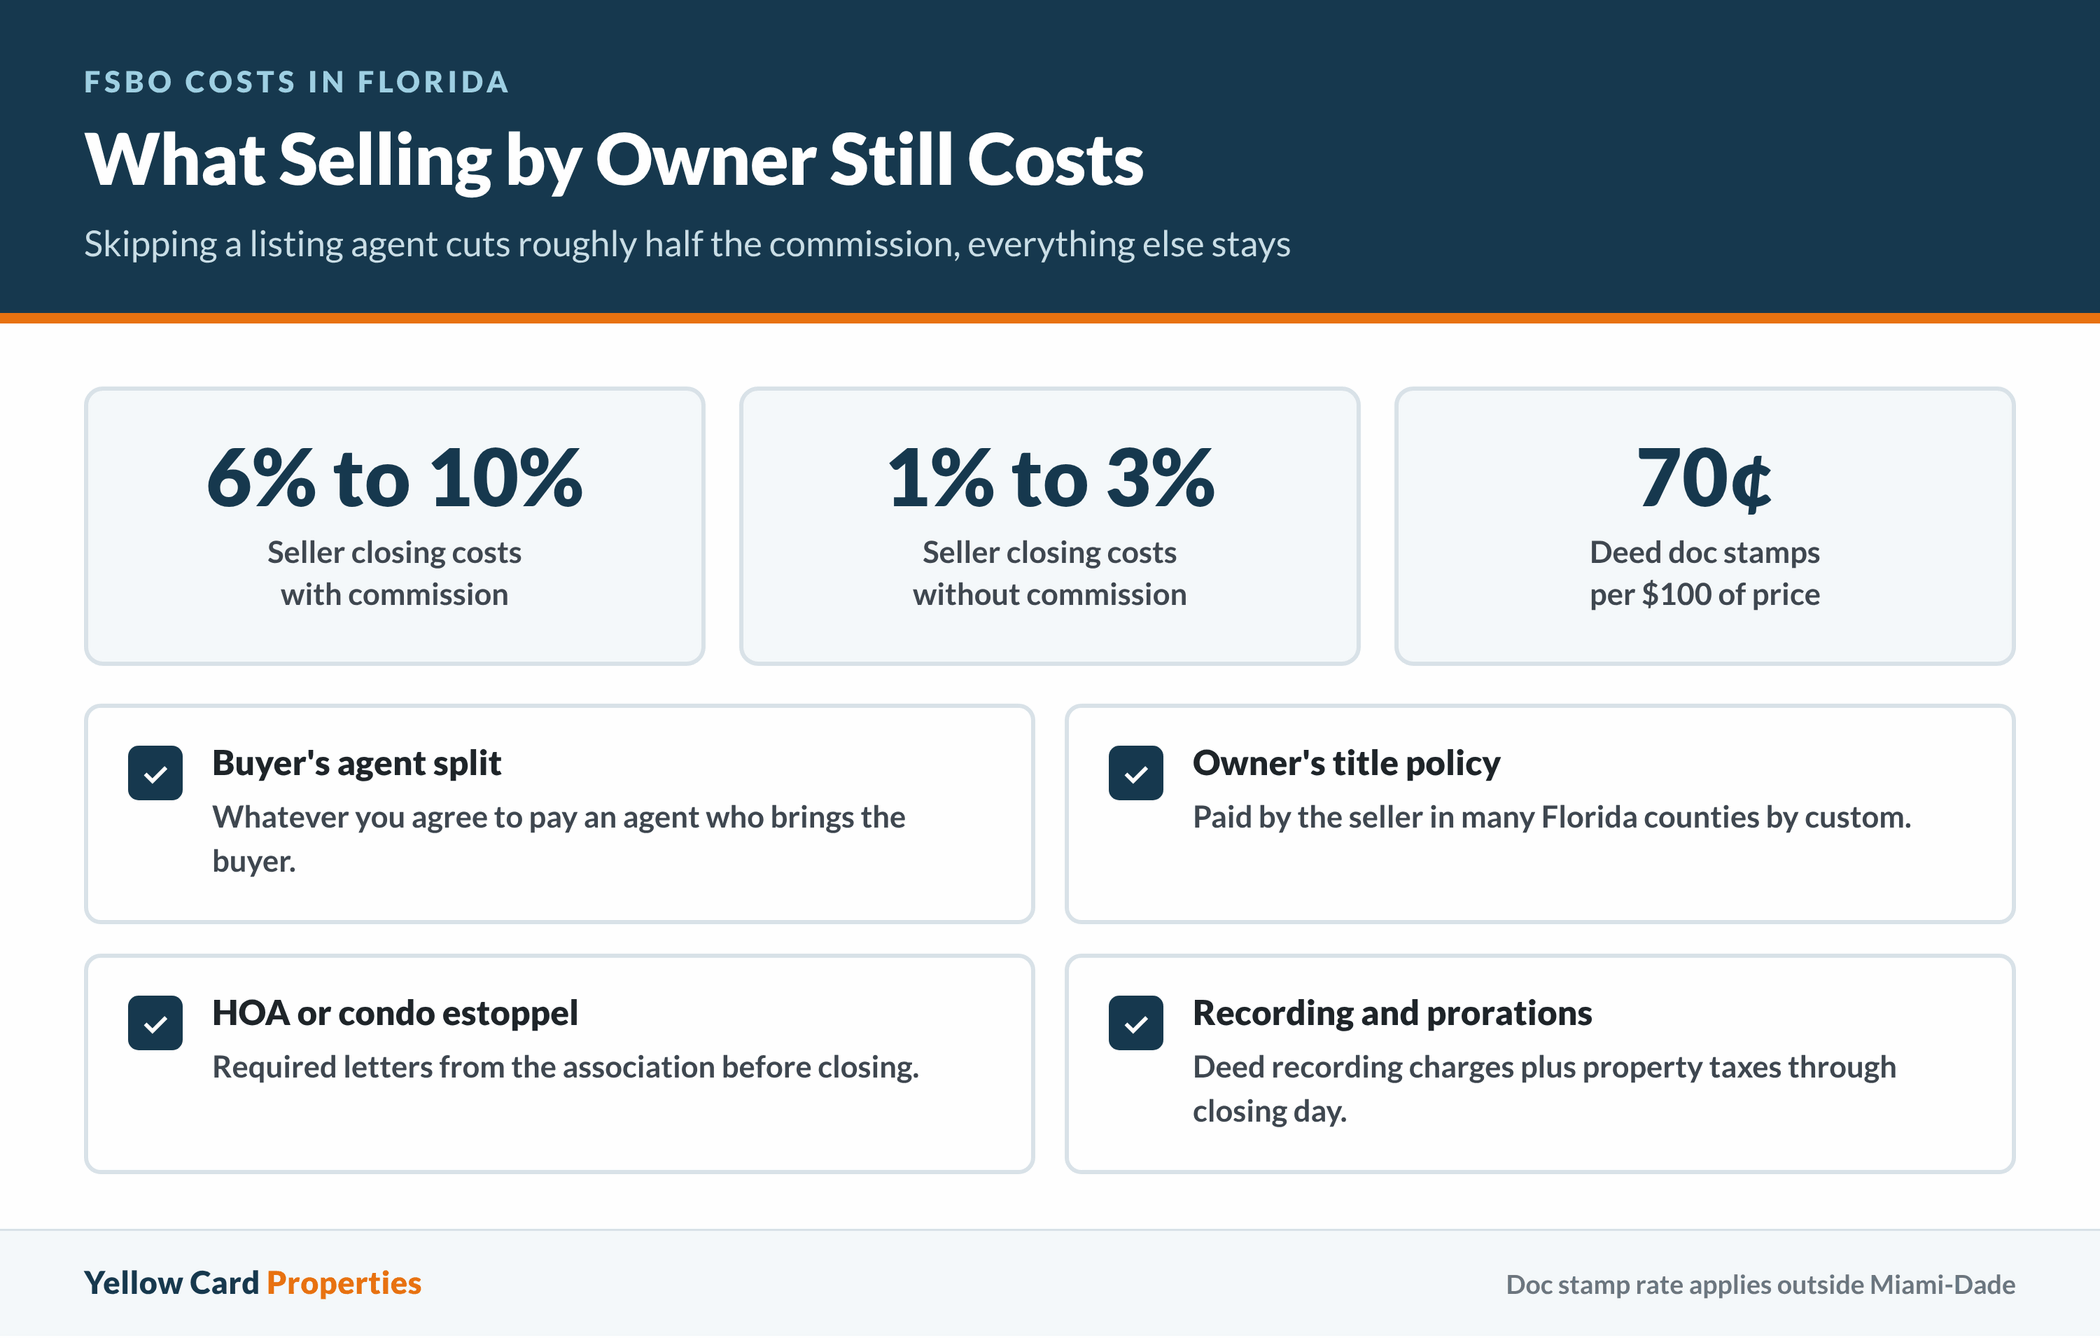
So FSBO costs in Florida realistically sit in that lower band, plus whatever you pay a buyer’s agent to bring you a buyer.
Going it alone is rarer than most people guess. NAR’s 2026 Profile found that 92 percent of sellers used an agent and only 5 percent sold by owner, which held at the smallest share they’ve ever recorded.
The price gap is worth a look too. NAR’s 2025 report put the median FSBO sale at $360,000 against $425,000 for agent-assisted sales. I’d still want that number in front of me before deciding.
A few years back I bought a rental in Palm Bay from a landlord who’d spent six years chasing rent on a house he inherited and never wanted. He’d tried selling it himself twice.
What Closing Costs Do FSBO Sellers Pay in Florida?
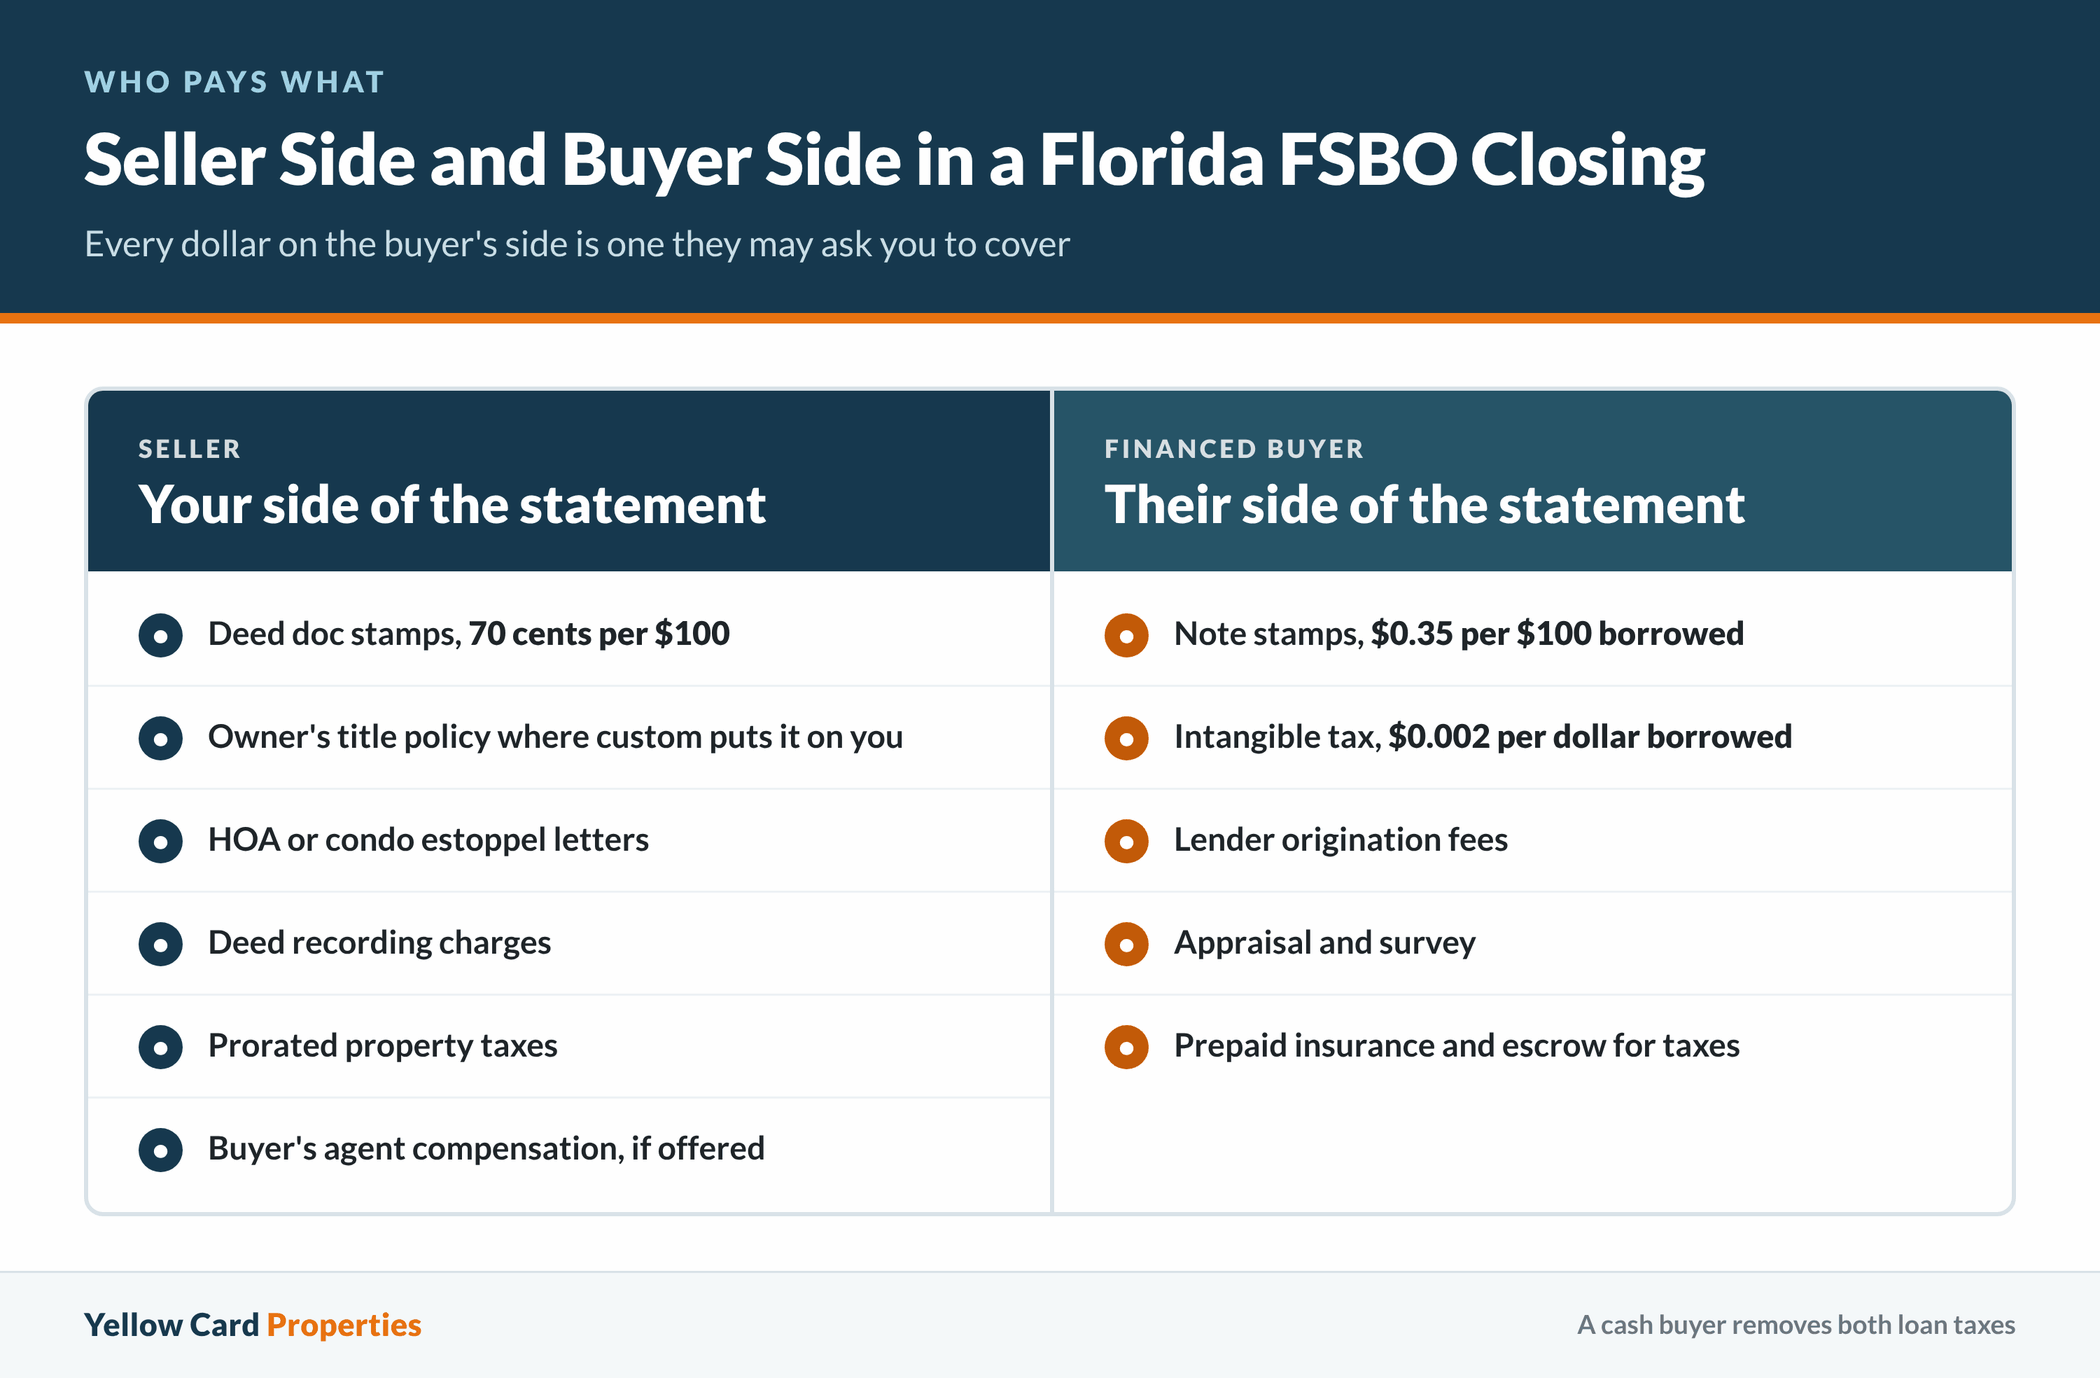
Start with the FSBO costs the state sets. The Florida Department of Revenue puts the deed tax at 70 cents per $100, or portion thereof, of total consideration in every county outside Miami-Dade. Sellers customarily pay it here, so it shows up whether or not you ever hired a Realtor. The Florida closing cost breakdown at Barnes Walker lays out the rate and the Miami-Dade exception and ties both to the statute.
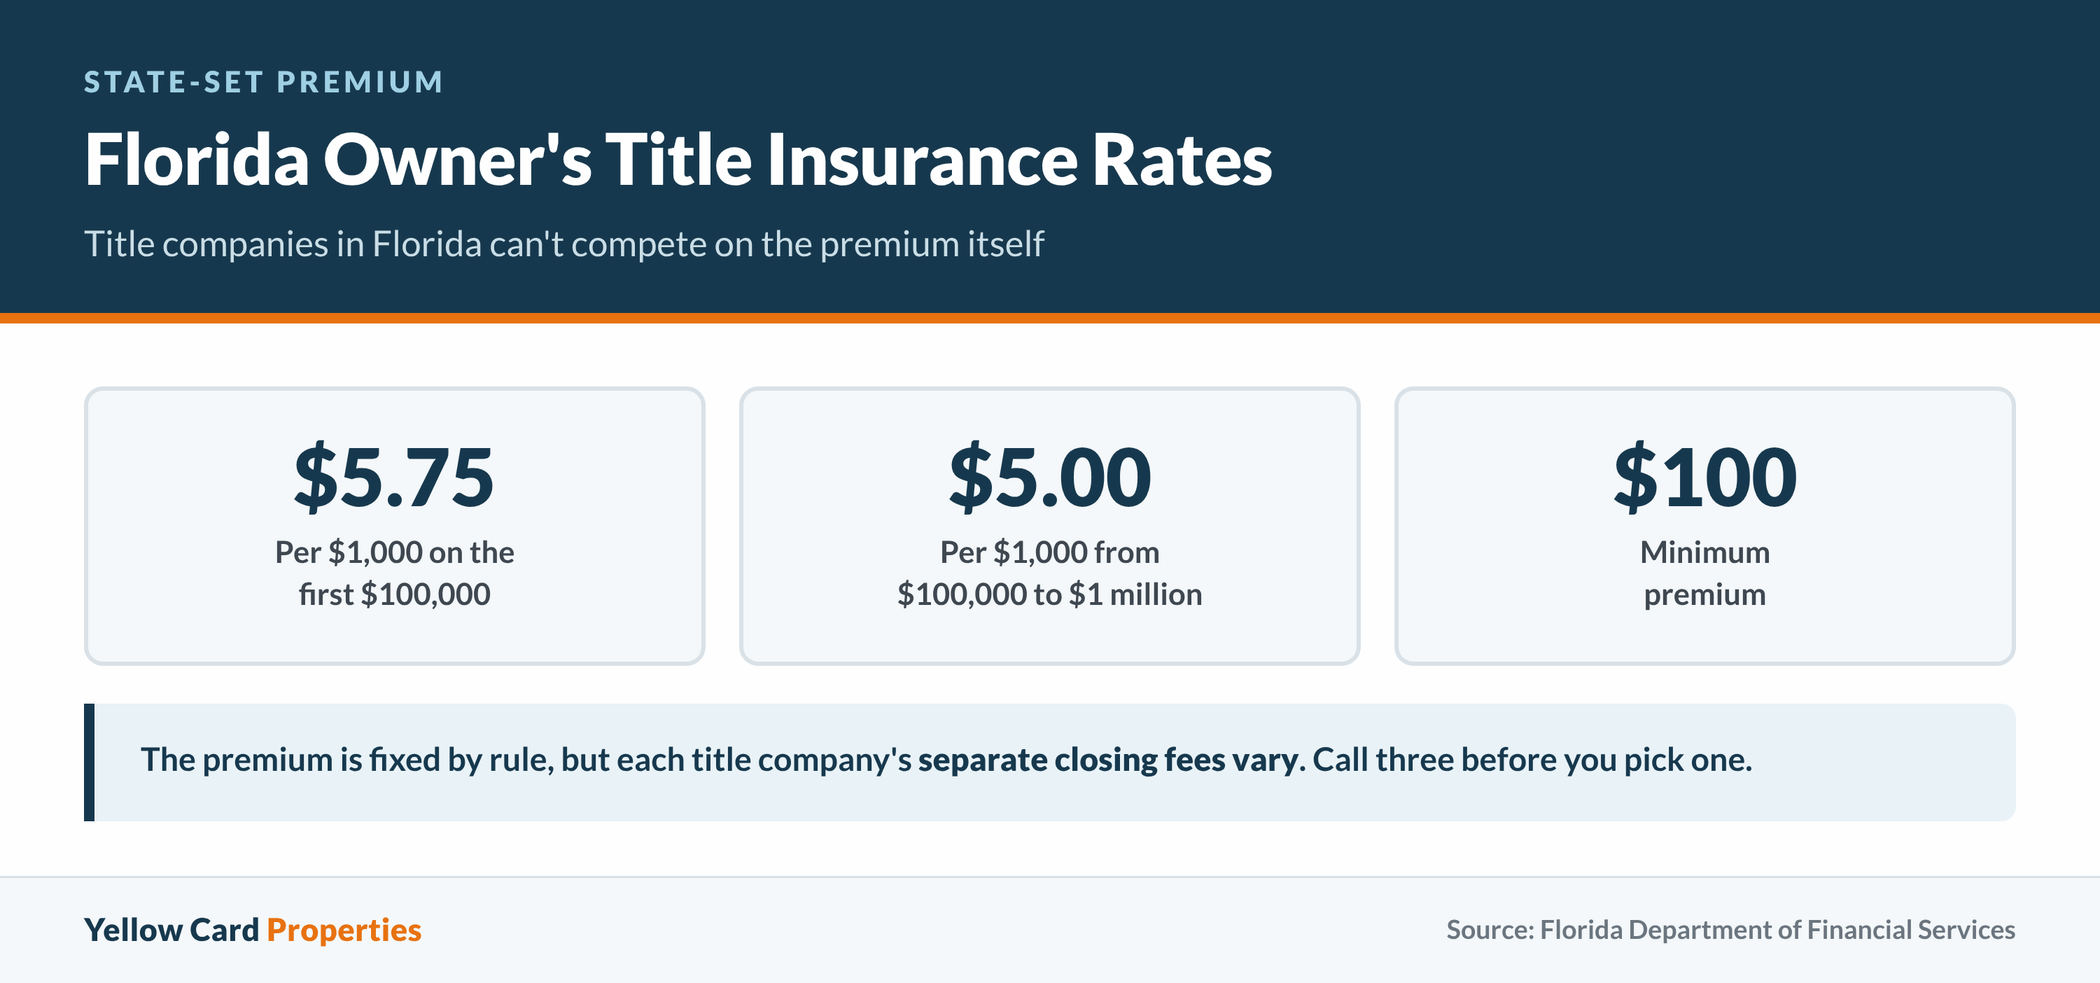
Title insurance is the second big one. Florida title companies aren’t allowed to compete on premium. The state’s rate for original owner coverage runs $5.75 per thousand on the first $100,000, then $5.00 per thousand up to a million, with a $100 minimum. You can check that schedule yourself at the Florida Department of Financial Services. In much of the state, custom puts that premium on the seller.
Then come the smaller items: HOA and condo estoppel letters, recording charges for the deed, prorated property taxes through the day of closing, and a payoff statement from your lender.
The concession line is what catches FSBO sellers off guard. Buyers in a slower Florida market ask for credits, and with no agent soaking up the first round of negotiation, those requests land on you. I’ve watched sellers brace for closing costs and get blindsided at the inspection table instead. FSBO costs in Florida often grow there, not at the signing table.
What Closing Costs Do Buyers Pay in a Florida FSBO Sale?
A cash buyer erases two state taxes from the closing entirely. The intangible tax on the mortgage and the doc stamps on the promissory note both hang on the loan. With no loan, they vanish in a cash sale. Your deed stamps as seller aren’t.
Financed Florida buyers carry a stack of their own. Note stamps run $0.35 per hundred borrowed and the intangible tax runs $0.002 per dollar borrowed, both on the buyer’s side. Add lender origination fees, the appraisal, a survey, prepaid insurance, and escrow deposits for taxes, and the buyer’s pile of costs grows fast. Buyer closing costs in Florida generally run a few percentage points.
That matters to you, because every dollar on the buyer’s side is a dollar they might ask you to cover. A buyer stretched thin on cash-to-close will come back for a seller credit, and that credit comes straight out of your net. I’ve watched sales in Cape Coral die in week five over a $6,000 gap neither side wanted to eat. Knowing the buyer-side FSBO costs in Florida helps you spot that gap before you accept the offer.
Homeowners insurance in Florida is its own headache. Buyers here often learn mid-contract that the premium on a 1998 roof in Lee County is double what they budgeted. That sinks contracts. If your roof or your four-point inspection has problems, price it in now rather than finding out at day forty.
Title company closing fees sit apart from the state-set premium, and those do vary quite a bit. You can’t shop for a lower premium. The extra closing fees each title company charges on top of it are fair game, though, so ask a few for a written fee sheet before you pick one. Call three. The spread is real.
How Do FSBO Costs Vary by Florida County?
For years I told sellers the deed tax was identical everywhere in Florida. I was wrong by one county.
Doc stamp and recording rates are set in Tallahassee, so Duval sellers and most others follow the same schedule. Miami-Dade is the one exception, with a 60-cent base rate plus a 45-cent surtax. That surtax doesn’t apply to a document transferring only a single-family dwelling. What actually changes from one county to the next is custom, not law.
Owner’s title insurance is the big one. In several Central Florida counties the seller customarily pays for the buyer’s owner’s policy, while in parts of South Florida the buyer covers it. That one custom can swing FSBO costs in Florida by thousands on the same house at the same price.
Property tax prorations shift by county too, because millage rates differ between, say, unincorporated Alachua County and the City of Gainesville. A mid-year closing in a high-millage city means a bigger proration credit to the buyer than the same closing date in a lower-millage area.
Days on market for Florida houses swing hard. Duval County’s median single-family price landed at $337,000 in October 2026, and homes went pending in a median of 31 days. Daytona Beach was another story. The median sale there in the three months ending October 2026 took 84 days to go pending, nine days longer than a year earlier. Every extra month you hold means another mortgage payment, another insurance bill, and another round of lawn service. Those carrying charges belong in your FSBO costs in Florida math just as much as doc stamps do. Our team at Yellow Card Properties works with these local customs every week, and we’ll give you a straight county-by-county read if you want one.
Which FSBO Costs Can You Negotiate?
Some line items bend more than sellers expect.
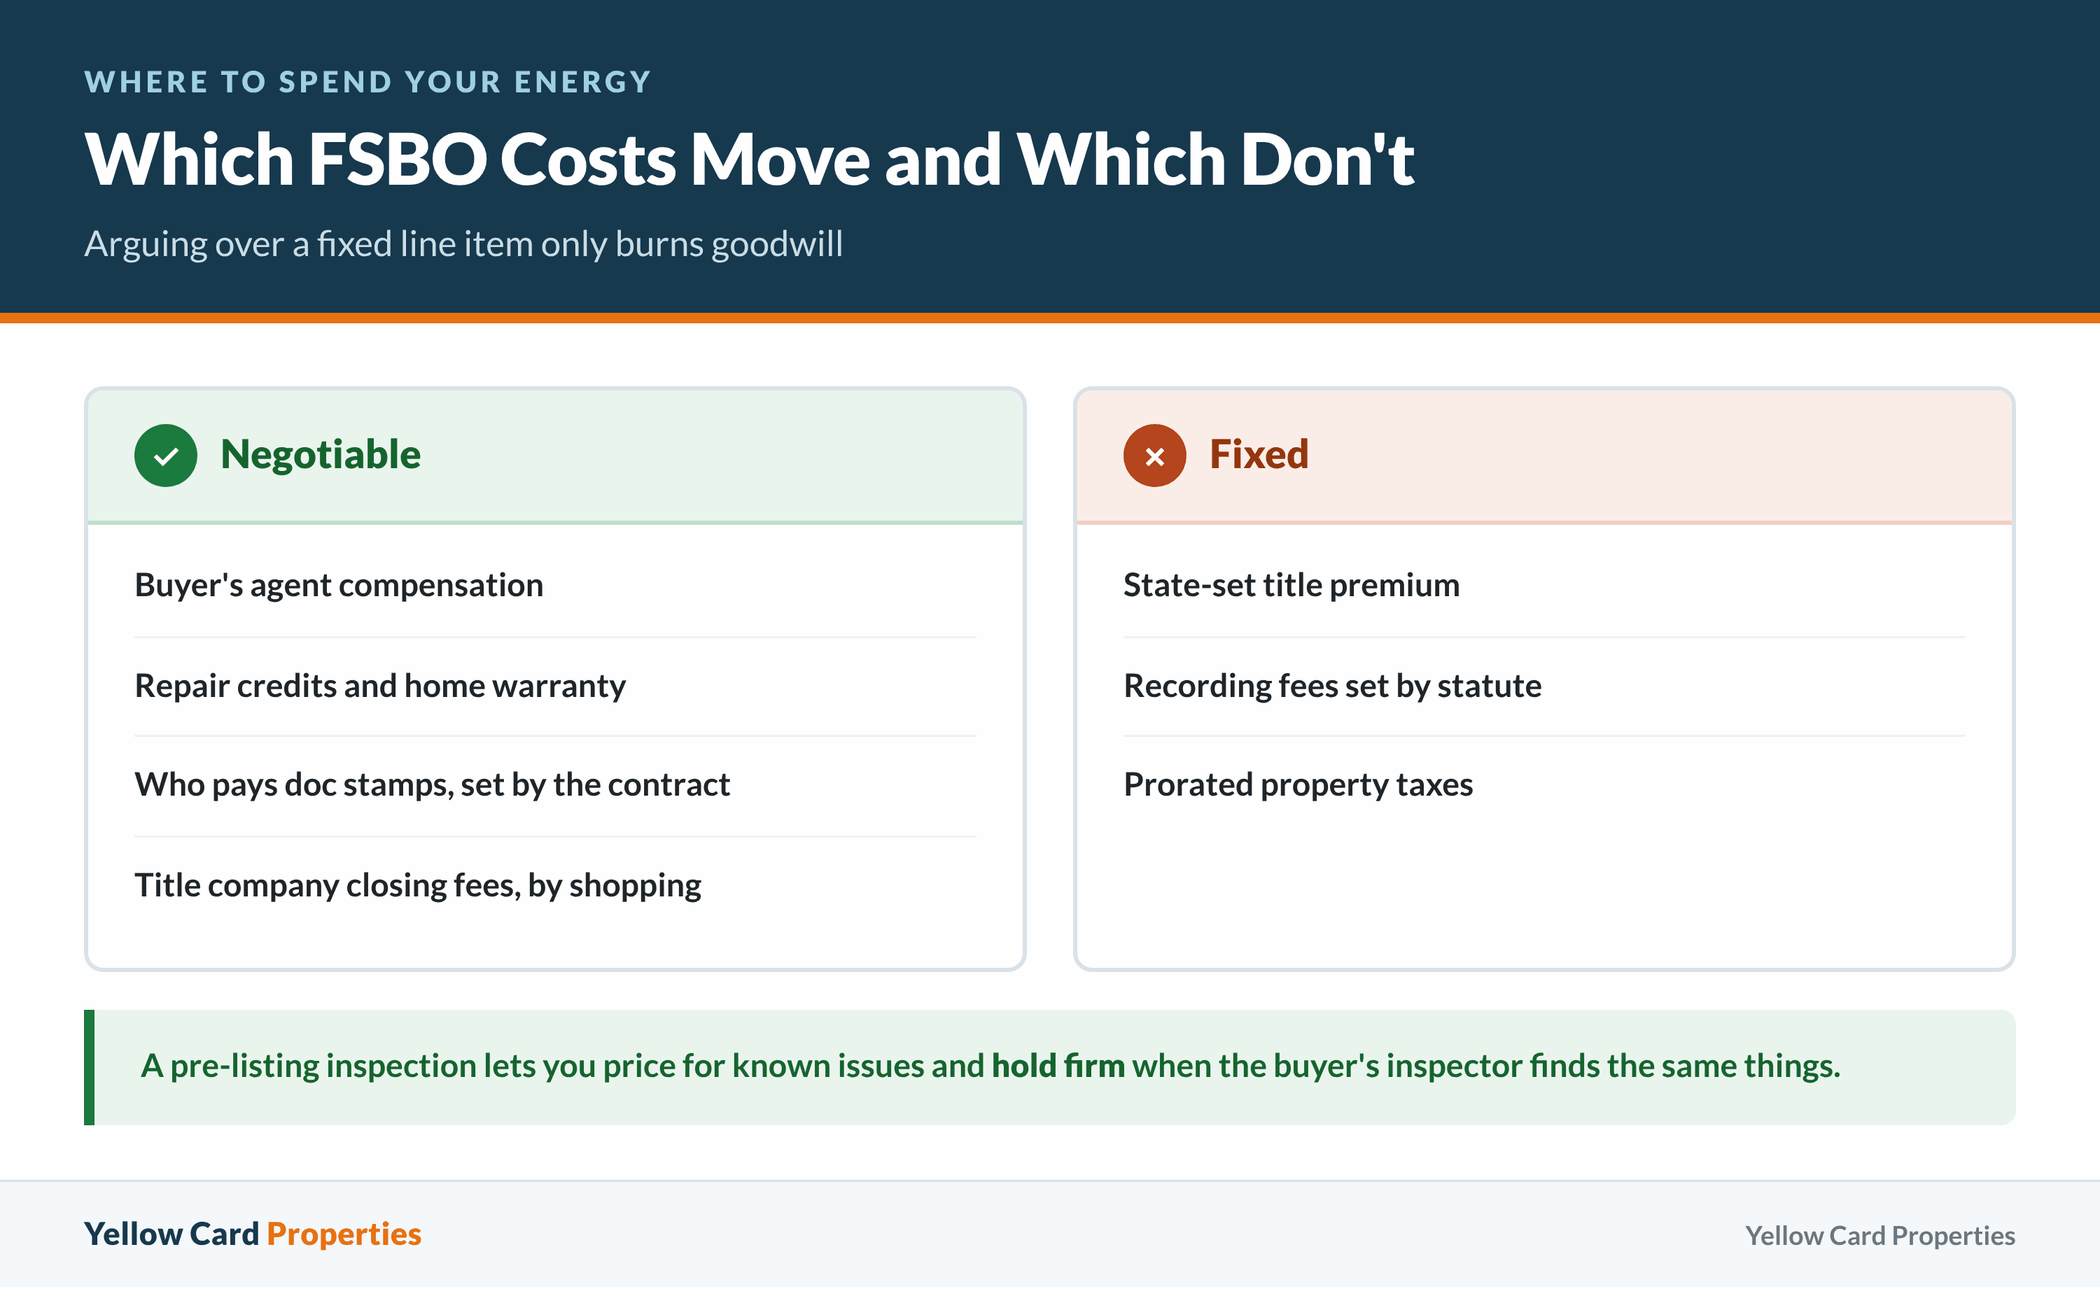
Custom assigns doc stamps to the seller, though the contract can shift them. The statute makes all parties liable, and the contract decides who writes the check. In a market where buyers have choices, you probably won’t win that one.
Buyer’s agent compensation is the single largest negotiable item among your FSBO costs. Plenty of sellers offer two and a half to three percent to pull in agent-represented buyers. Plenty of others offer nothing and sell to an unrepresented buyer. My take isn’t the popular one: refusing to pay any buyer-side commission shrinks your pool more than it saves you. Offer something reasonable and get the traffic.
Home warranty and repair credits are the FSBO costs where discipline pays off. Order a pre-listing inspection and price the house to match, then hold firm when the buyer’s inspector finds the same things. Sellers who skip that step negotiate twice, first on price and again on repairs.
The state-set title premium is fixed by rule. Recording fees are statutory. Prorated taxes are arithmetic, not opinion. Once you know which FSBO costs in Florida are truly fixed, you won’t burn goodwill arguing over a line item that can’t change. Put your energy into the three or four items that actually move.
What Tools Can Lower Your FSBO Costs in Florida?
Flat-fee MLS is the single highest-return tool for cutting FSBO costs in Florida. You pay a licensed brokerage a one-time fee to put your listing on the MLS, which feeds Zillow, Realtor.com, and every agent’s search.
A real estate attorney is the second tool, and I’d argue it’s underused. Florida lets attorneys handle closings, and a flat-fee contract review runs a fraction of a commission.
Net sheet calculators help, but only when you feed them your real FSBO costs. Build your net sheet from your actual loan payoff and written fee estimates, not one flat percentage.
Pricing is a tool too. Statewide, Florida listings took a median 81 days in September 2026, and 20.1 percent of them had a price cut. One in five sellers mispriced badly enough to correct in public. A price cut costs you more than any closing line item. It resets your days-on-market clock and signals weakness to every buyer watching.
Those are FSBO costs that pay for themselves. Skipping them to save three hundred dollars on a $400,000 Florida listing is the worst trade in this whole business.
How Do You Get a Free Estimate of Your FSBO Costs?
Skipping this math on FSBO costs is how sellers lose thousands at closing. A useful estimate of FSBO costs in Florida needs four inputs. You’ll want your realistic sale price, your loan payoff with interest through the closing date, your county’s title custom, and your HOA status.
Title companies throughout Florida will run a seller net sheet for free. They want your closing business, so the estimate costs you nothing, and it’s built on real rate tables instead of a web form. Ask for it in writing with every line itemized.
Your county property appraiser’s site shows the taxable value and current millage, and those drive your proration.
For a price anchor, pull comparable closed sales instead of active listings. Closed sales tell you what Florida buyers paid. Across Broward and Palm Beach over the twelve months ending September 2026, 77 percent of Broward sales and 80 percent of Palm Beach sales closed below list price. Price from the closed column.
A written offer with no commission, no concessions, and a firm closing date gives you a floor to measure your FSBO numbers against. Yellow Card Properties will put that in writing without asking you to list. Hold it up against your net sheet and you’ll know fast whether selling by owner is worth the months it’ll take.
How Do You Close a Florida FSBO Sale Without Overpaying?
That comparison is really the whole exercise. You’ve got a net number from a FSBO path that takes two to four months, and a net number from a direct sale that takes two to four weeks. Subtract the carrying costs from the longer one before you decide which is bigger.
Pick your closing agent early. Whoever handles escrow on your closing controls the timeline, the title search, and the payoff coordination. A slow title agent can add three weeks to a Florida closing for no good reason.
Use the standard Florida contract forms instead of something you found online. The FR/BAR and CRSP forms spell out inspection periods, financing contingencies, and who pays what. A homemade contract is where FSBO costs in Florida quietly multiply, since any vague clause tends to get read against the person who wrote it.
Keep every disclosure in writing. Florida sellers owe buyers disclosure of known material defects that aren’t readily observable. That duty doesn’t soften because you sold without an agent.
Before you take the house off the market, verify the buyer. For cash, that means proof of funds. For financing, it’s a real preapproval letter with the loan officer’s direct line. I’ve seen sellers lose six weeks to a buyer whose “approval” was an online prequalification form.
A couple splitting assets in a divorce reached out about a Winter Haven ranch house last spring. Neither wanted to coordinate showings with the other, and both sets of boxes were still stacked against the back wall of the garage. What they wanted most was a date on a calendar. We gave them one.
Frequently Asked Questions
What Will It Cost Me to Close on a $400,000 House in Florida?
Without a listing agent, your controllable FSBO costs at that price come down to a handful of items. You’ve got the state deed tax, the owner’s title policy if your county’s custom puts it on you, recording fees, your HOA estoppel, and prorated taxes. Add whatever you’ve agreed to pay a buyer’s agent. Run the deed tax rate and the title rate schedule above against your price, and you’ll land within a few hundred dollars of the real number.
How Much Are Closing Costs on a $250,000 Florida Home?
The same line items apply, just scaled down, since the deed tax and the title premium are both figured per hundred or per thousand dollars of price. The flat ones don’t scale: recording charges, estoppel, courier, and document prep. Those make up a bigger slice of a smaller sale, so FSBO costs in Florida tend to run a slightly higher percentage at lower price points.
Do I Have to Pay a Buyer’s Agent If I Sell My Own House?
No law requires it. If you want agent-represented buyers walking through your door, though, offering compensation in the listing is how that happens. You can also negotiate it as a credit in the contract instead of advertising it upfront, which leaves room to keep more if an unrepresented buyer finds you first.
Can I Skip Title Insurance to Reduce My FSBO Costs in Florida?
As the seller, you don’t need a new policy yourself. Your buyer’s lender will require one, though, and any sensible cash buyer will want an owner’s policy too. Since state rule sets the premium, there’s no cheaper version to hunt for. What you can shop is the closing agent’s separate fees, and those differ enough to be worth three phone calls.
Does Selling by Owner Mean I’ll Net More Money?
Sometimes, and it usually comes down to pricing accuracy and how long the house sits. A FSBO seller who prices right and closes in a month often beats a listed sale after commission. One who overprices, cuts twice, and carries the house through a Florida summer of insurance and tax payments usually doesn’t. Your carrying cost per month is the number to watch.
Who Handles the Paperwork in a Florida FSBO Closing?
A title company or a real estate attorney does the heavy lifting: title search, lien payoffs, preparing the deed, collecting and sending out funds, and recording with the county. You’re on the hook for the purchase contract and your disclosures. That’s a reasonable split, and it’s why so many FSBO costs in Florida turn out manageable once you know what’s coming.
If you’re weighing a FSBO sale and want a second set of eyes on the numbers, we’re glad to look at them with you. There’s no listing agreement, no pressure, and nothing owed. Sometimes selling by owner is clearly the right call, and we’ll tell you so. Other times a direct sale nets more once FSBO costs and carrying charges are counted, and we’ll show you that math too. Either way, you’ll walk away knowing where you stand.
Selling by Owner in the Jacksonville Area
Prices around the Jacksonville area have cooled a bit. The metro’s median home price sat near $380,000 in October 2026, down 4.8 percent from a year earlier. In a softer market, buyers push harder for credits, and you field every one of those requests yourself when you sell by owner.
We buy houses from homeowners across Florida, so we can show you what a direct sale nets next to your FSBO numbers.
Compare Your FSBO Numbers With a Cash Offer
If you’d like a second look at your net sheet, contact Yellow Card Properties and we’ll go through it with you. You can also fill out the form below to tell us about your house, with no obligation.